
プライベート税務
インボイス経過措置の見直しと2026年10月からの実務対応
適格請求書発行事業者以外の事業者からの課税仕入れに適用される経過措置について、2026年10月1日から仕入税額の控除割合が80%から70%に引き下げられました。本稿では、今回の引き下げに伴う実務上の留意点について整理します。
2026/02/04 読了時間 1 分
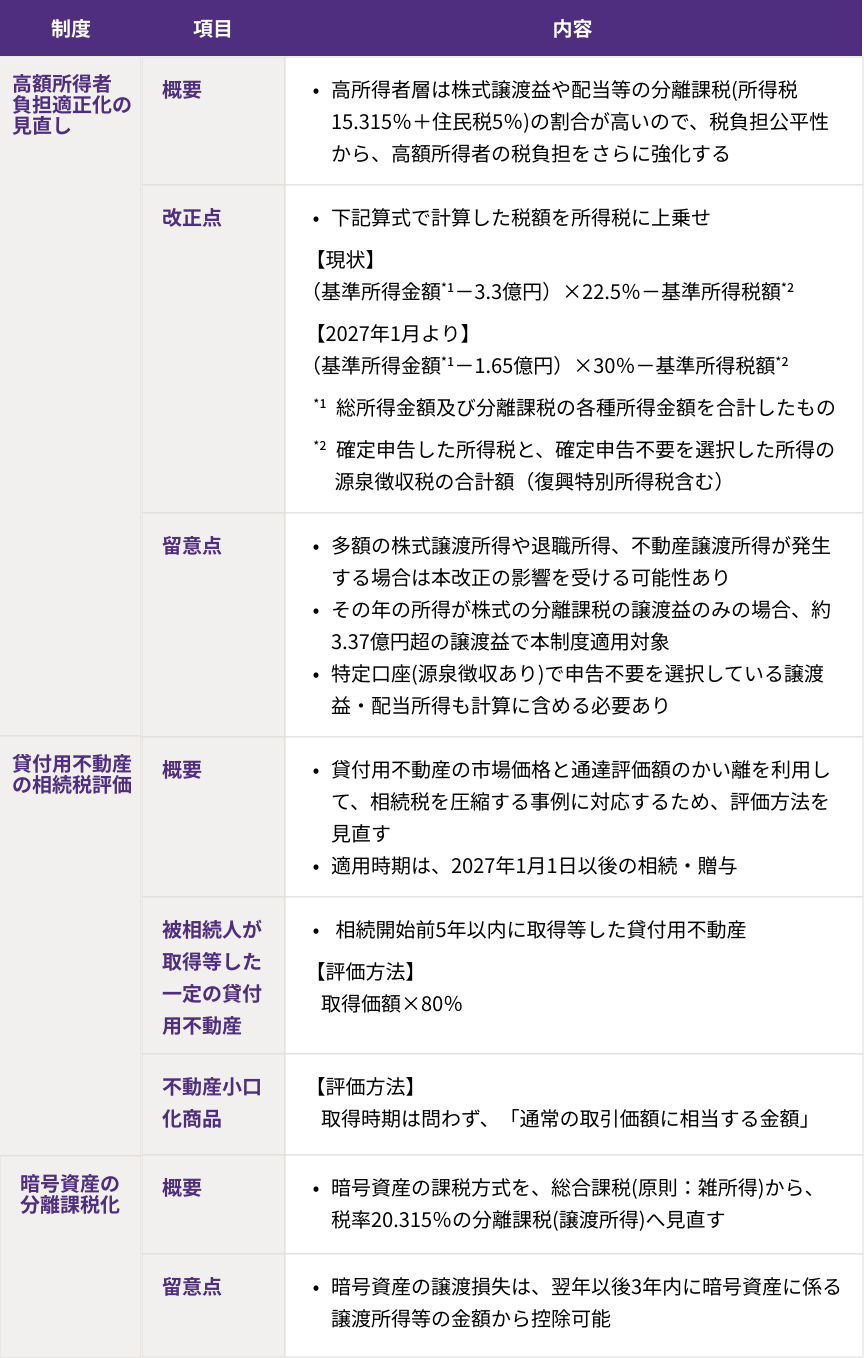
2026年度の税制改正大綱が公表されました。個人に関連する主な改正はつぎのとおりです。
NISA口座は、18歳以上が口座開設可能な年齢でしたが、2027年1月1日以降は年齢制限を撤廃し、0歳から口座開設可能となり、年間60万円(非課税保有限度額600万円)を上限に投資が可能となります。
■ 2026年度 税制改正 解説資料・オンデマンド配信のご案内
本インサイトで取り上げた税制改正について、より詳しく解説した資料およびオンデマンド配信をご案内しています。あわせてご活用ください。
2026年度 税制改正 解説動画(オンデマンド配信を視聴)
※ オンデマンド配信は期間限定での公開となります(2026年1月19日~3月31日)

適格請求書発行事業者以外の事業者からの課税仕入れに適用される経過措置について、2026年10月1日から仕入税額の控除割合が80%から70%に引き下げられました。本稿では、今回の引き下げに伴う実務上の留意点について整理します。
円安は個人が保有する資産の税務にも影響を与えています。例えば円安の影響でドルを保有している個人がドルをユーロに変更したときや、ドルで外国株を購入したときは円に戻さない場合であっても為替差益に注意が必要です。その他にも円安が個人の税務に与える様々な影響を整理し、その留意点をまとめます。
令和8年度税制改正にて、特定暗号資産の所得税の取扱いが総合課税から申告分離課税に改正されました。当該改正によって、今後、暗号資産の譲渡の増加が見込まれますが、ミニマムタックスに留意する必要があります。
令和8年度税制改正により新設された、関連者間取引に係る書類の整理保存の特例(法人税法施行規則第59条の2)では、すべての青色申告法人に対し、対価の設定方法等を補完する書類の保存が義務付けられます。本稿では、未対応時の青色申告取消リスクに備えるため、主な改正点を整理するとともに、国税庁の事務運営指針に基づく具体的な実務対応を簡潔に解説します。
The FY2026 Tax Reform Outline (published Dec 12, 2025) introduces tighter documentation rules for intra-group transactions, affecting companies of all sizes. This measure specifically targets arbitrary pricing or lack of documentation for intra-group services (including IP transfers and loans), such as shared cost facilities.
On 19 December 2025, Japan’s ruling coalition released the outline of the fiscal year 2026 (Reiwa 8) tax reform proposals. While the proposals introduce several individual amendments to corporate and international tax rules, collectively they reflect a broader recalibration of Japan’s tax policy - one that prioritizes strategic investment, domestic economic substance, and tighter alignment between incentives and measurable outcomes.The proposals reflect a clear policy shift toward targeted incentives that support capital formation, advanced technology development, and economic security, while simultaneously tightening eligibility criteria, reducing reliance on broad-based tax benefits, and strengthening compliance expectations. This article summarizes the key corporate and international tax measures based on publications issued by the Ministry of Finance.